
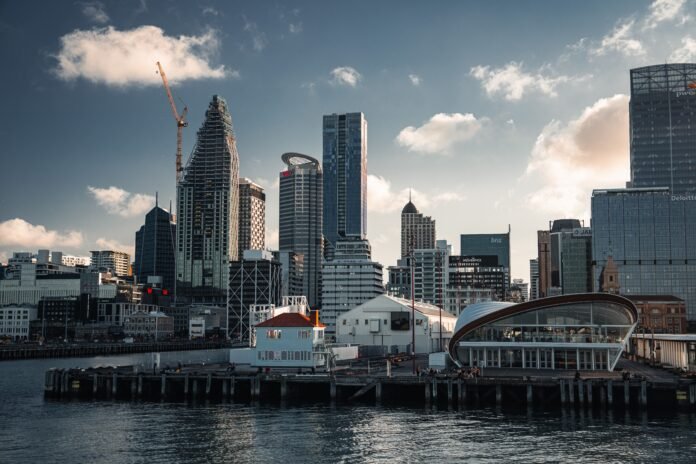
Expanding operations into Oceania offers significant growth potential, and New Zealand has become a prime destination for international companies. According to recent economic data, total foreign investment in the country recently reached an impressive $633.8 billion. This influx of capital is driven largely by a mature corporate market, a highly transparent regulatory environment, and a skilled workforce. However, successfully establishing a footprint in a new country requires much more than simply opening an office or hiring local staff. Corporate leaders must carefully navigate a unique financial landscape, adjusting their operational logistics to meet local statutory requirements. Understanding the specific financial steps for entering this market is vital for ensuring long-term profitability and avoiding costly regulatory missteps.
Navigating Initial Setup and Regulatory Registrations
The moment a foreign company decides to commence business activities in the country, a strict compliance clock begins ticking. Overseas businesses are legally required to enroll on the New Zealand Companies Office Overseas Register within exactly 10 working days of starting operations. Furthermore, any newly formed subsidiary must appoint at least one company director who actively resides in New Zealand or a recognized enforcement country like Australia. Failing to meet these initial incorporation timelines can result in immediate penalties and delay your ability to secure local bank accounts.
Alongside corporate registration, incoming companies must immediately assess their tax liabilities. Goods and Services Tax is a crucial component of local operations, and it can be highly nuanced for foreign entities. Identifying the correct registration category early prevents future invoicing issues and ensures smooth cross-border transactions. Building a strong foundation and securing expert Bookkeeping & accounting compliance in New Zealand will ensure your business can correctly reclaim GST on valid local expenses.
As part of the setup, the New Zealand Inland Revenue Department outlines five distinct types of GST registration for overseas businesses, depending on specific circumstances like supplying remote services or importing low-value goods. Properly registering under the right category is the first step toward long-term operational success and avoids hefty fines from regulatory bodies.
Mastering Corporate Tax and Payroll Obligations
Once registered, financial leaders must adapt their strategies to align with local tax structures and employee benefit programs. New Zealand applies a straightforward, flat corporate income tax rate of 28 percent on the locally sourced income of non-resident businesses and branches. While the rate is flat, calculating taxable income requires a deep understanding of allowable deductions. For instance, recent policies allow companies to immediately deduct 20 percent of the cost of new business assets from their taxable income, providing a significant incentive for business expansion.
Payroll management also demands proactive attention, particularly regarding the national KiwiSaver retirement program. Taking effect in April 2026, the default employer and employee contribution rates will increase from 3 percent to 3.5 percent. Companies must adjust their internal payroll software and budgets ahead of time to accommodate this shift. Staying ahead of these local regulatory deadlines does more than just avoid fines. Industry experts often highlight why timely tax filings protect your business reputation, as strict adherence to local compliance acts as a strong signal of your company’s stability and reliability to new vendors, clients, and lenders.
Ensuring Long-Term Reporting and Audit Readiness
The standard financial year for New Zealand businesses runs from April 1 to March 31. Incoming foreign companies typically need to align their income tax returns and provisional tax installments to this schedule. Sometimes, parent companies operating on a standard calendar year may apply for a different balance date to streamline their global reporting, but this requires formal approval from Inland Revenue. Careful planning is needed to transition smoothly between different financial calendars.
Maintaining ongoing compliance involves strict data retention and reporting protocols. The External Reporting Board sets the mandatory accounting standards, which utilize a tiered framework based on entity size. To ensure your expanding business remains audit-ready, you should implement the following internal practices:
- Retain all commercial contracts, payroll documentation, and invoices for a minimum of seven years to satisfy statutory audit requirements.
- Prepare for dual reporting obligations if operating as a large overseas branch, which requires filing separate audited financial statements for worldwide operations and local activities.
- Monitor subsidiary asset and revenue thresholds, as meeting the $22 million asset or $11 million revenue mark automatically classifies a company as large and triggers mandatory annual audits.
Expanding into the New Zealand market offers an exciting avenue for international growth, provided the financial foundation is solid. From navigating initial GST registrations and adjusting to KiwiSaver increases to mastering dual reporting requirements, every step requires precision. By proactively addressing these financial obligations and prioritizing accurate record keeping, global businesses can successfully integrate into the local economy. A well-planned financial strategy not only safeguards the company against compliance penalties but also establishes a reputable, resilient brand in a competitive new market.