
For Torrance homeowners, choosing insurance in 2026 involves more than just comparing monthly bills. Coastal weather, occasional intense rain, wind, aging roofs, water damage, earthquakes, and rebuilding costs can all affect the protection a household needs. Reviewing insurance rates Torrance can be a useful starting point, but the best comparison also considers deductibles, exclusions, limits, and the details of the property itself.
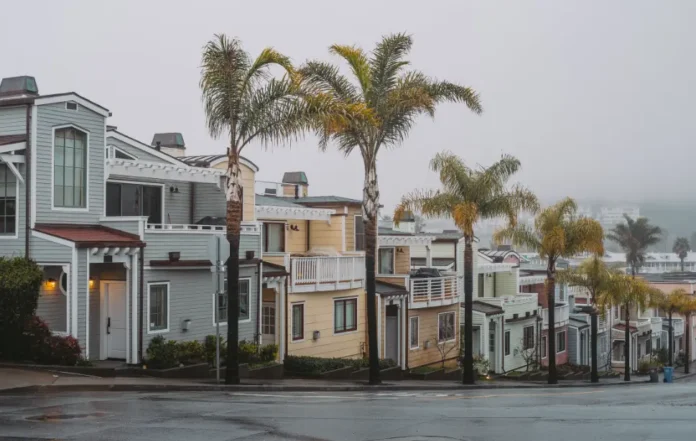
Torrance sits in the South Bay, where homes may experience marine air, seasonal rain, drainage concerns, heat, and wind exposure. A property near the coast may have different maintenance needs than a home farther inland, while a remodeled house, an older roof, a detached garage, or a home office can raise additional insurance questions. The goal is not to predict every event, but to understand which losses a policy is designed to address.
Key Takeaways
- Homeowners should review coverage when they renovate, replace a roof, buy major items, or receive a renewal notice.
- Flood and earthquake damage are commonly excluded from standard homeowners policies and may require separate protection.
- A lower premium can come with a higher deductible, narrower coverage, or lower limits.
- Updated records, maintenance, and accurate home details can make a future claim easier to support.
- In Torrance, comparing policies should include local water, wind, coastal exposure, and earthquake considerations.
Why Climate and Property Risk Matter in Torrance
Insurance companies assess the likelihood and potential cost of claims when pricing a home policy. That evaluation can include a home’s construction, roof condition, replacement cost, prior losses, location, and nearby hazards. Two Torrance homes may receive different quotes even when they are only a few miles apart because their age, building features, claims history, and policy choices differ.
Rebuilding costs matter as much as weather risk. Labor, materials, permitting, and the need to meet current building codes can affect the cost of repairing a damaged home. The California Department of Insurance explains that dwelling coverage should reflect rebuilding cost rather than a home’s market value, since land value and real estate prices are not the same as the cost to reconstruct a structure.
A Torrance Homeowner’s Risk Checklist
Rain, drainage, and flooding
Heavy rain can reveal clogged gutters, poor grading, roof leaks, overwhelmed drains, and sewer backup concerns. Standard homeowners coverage may address certain sudden and accidental water losses, but it does not automatically cover every source of water damage. In particular, most standard policies do not cover flooding. Homeowners can review how flood insurance protects buildings and belongings from flood damage before assuming their regular policy fills that gap.
Wind, roofs, and exterior features
Wind can damage roof coverings, fencing, patio furniture, trees, gates, and outdoor equipment. Check the roof’s age, fastening, flashing, and maintenance records. Secure loose outdoor items before severe weather, and understand whether the policy has a special wind or hail deductible.
Earthquake exposure
Earthquake risk remains an important consideration in California, including for homes that have not experienced shaking-related damage before. Standard homeowners policies generally exclude earthquake and earth movement losses. Ask whether earthquake coverage is available separately, what deductible applies, and whether the limit fits the home and belongings.
Water and system failures
Water heaters, washing machine hoses, supply lines, drains, sump pumps, and sewer lines deserve attention. Coverage can depend on whether damage was sudden and accidental, gradual, caused by maintenance issues, or linked to a backup. Read the policy rather than relying on a broad assumption that “water damage” is always covered.
What a Standard Home Policy May Include
Although wording varies by insurer and policy form, homeowners coverage often includes several basic sections:
- Dwelling coverage: Protection for the main home after a covered loss.
- Other structures coverage: Coverage for qualifying detached structures, such as garages, sheds, or fences.
- Personal property coverage: Protection for belongings such as furniture, clothing, and appliances, subject to limits and terms.
- Loss of use coverage: Help with eligible temporary living expenses when a covered loss makes the home uninhabitable.
- Liability coverage: Protection for certain claims involving injuries or property damage for which the homeowner may be legally responsible.
Look Beyond the Premium
A quote should be evaluated as a package, not just a price. Before selecting or renewing a policy, compare these details:
- The annual premium and payment schedule.
- The standard deductible and any separate deductibles for wind, wildfire, or other losses.
- The dwelling limit and whether it reflects current rebuilding costs.
- Personal property limits, including limits for jewelry, electronics, tools, or collectibles.
- Loss of use coverage for temporary housing after a covered claim.
- Exclusions for flood, earthquake, maintenance-related damage, mold, or sewer backup.
- Whether belongings are settled at replacement cost or actual cash value.
Replacement Cost Versus Actual Cash Value
Replacement cost coverage generally pays the amount needed to repair or replace covered property with comparable new property, subject to policy terms and limits. Actual cash value generally accounts for depreciation. For example, an older sofa or an aging roof may have less actual cash value than the cost of a replacement. This distinction can have a meaningful effect after a major claim.
After a kitchen remodel, room addition, solar installation, or substantial purchase, update the insurer with accurate details. A policy written for an earlier version of the home may not fully reflect its current features or replacement needs.
A 30-Minute Torrance Insurance Review
- Minutes 1 to 5: Find the declarations page, renewal notice, and endorsements.
- Minutes 6 to 10: Write down dwelling limits, personal property limits, deductibles, and loss of use coverage.
- Minutes 11 to 15: List renovations, roof work, major purchases, and home-business equipment.
- Minutes 16 to 20: Identify possible flood, earthquake, water backup, and valuable-item gaps.
- Minutes 21 to 25: Take photos or video of rooms, exterior features, and major possessions.
- Minutes 26 to 30: Prepare specific questions for an insurer, agent, or broker before changing coverage.
Practical Improvements That Support Preparedness
Risk reduction does not guarantee a lower premium or coverage approval, but sensible maintenance can help protect the property. Keep gutters and drains clear, maintain roof seals, trim vegetation away from structures, test smoke and carbon monoxide alarms, use leak sensors near appliances, and store receipts and renovation records outside the home or in secure digital storage.
Conclusion
Home insurance decisions in Torrance should reflect the realities of the property and the community, not simply the lowest advertised price. By reviewing rebuilding limits, water and earthquake gaps, deductibles, valuables, and temporary housing coverage before renewal, homeowners can make more informed choices. A policy is most useful when its protections, exclusions, and costs are understood well before a claim is needed.